To calculate your car accident claim value, add your economic and non-economic damages, then reduce the total by your share of fault. Comparing that figure with the available insurance shows what a fair settlement can realistically collect, before fees and liens.
The adjuster’s offer came in fast, and you can’t tell whether it covers the ER bill from UMC, the shifts you missed, or neck pain that wakes you at 3 a.m. Once you sign the release, that number is almost always final, even if your doctor later orders a surgery. Our Las Vegas car accident lawyers at Ace Law Group help review your settlement offer and negotiate a fair value before you accept it. The four steps below show how that number is built.
Recent Case Result
We secured a $5 Million settlement for a client injured in a car crash.
Our legal team fought to recover full compensation for medical expenses, lost wages, and pain and suffering.
Call Us Now: (702) 333-4223Key Takeaways – Steps to Calculate a Car Accident Settlement
- Formula: Economic damages plus non-economic damages, reduced by your fault percentage and limited by available insurance.
- Shared fault: Your award is reduced by your fault percentage. Fault greater than the combined fault of the drivers you sue (more than 50%) bars recovery under NRS 41.141.
- Insurance limits: Nevada’s minimum liability policy pays up to $25,000 per injured person. Your own underinsured motorist (UIM) coverage, if you carry one, can pay damages above that limit.
- Gross vs. net: Attorney fees, case costs, and medical liens come out of the settlement before you receive a check.
Step 1: Estimate Your Economic Damages (Measurable Financial Losses)
Economic damages in a car accident are the actual expenses and lost pay the crash put on you. Each one comes with a document, such as an invoice, a receipt, or a pay stub. Five carry the most weight in your claim value:
| Economic Damage | How to Calculate It | Proof to Preserve |
|---|---|---|
| Past Medical Expenses | Add every bill for the ambulance, ER, imaging, surgery, physical therapy, and prescriptions | Itemized bills and treatment records |
| Future Medical Expenses | Price the care your doctor expects you to need | Treating physician’s opinion or a life care plan |
| Lost Wages | Hourly rate × hours missed, or daily salary × workdays missed | Pay stubs and an employer letter |
| Lost Earning Capacity | Measure the gap between what you could earn before the crash and what you can earn now | Vocational and economic expert reports |
| Property Damage | Add the vehicle’s repair cost, or the car’s actual cash value (ACV) if it’s totaled, plus rental costs and damaged personal items | Repair estimates and valuation reports |
Total loss valuations, rental costs, and diminished value each follow their own rules, covered in our guide to property damage claims.
Add these losses together. The total is your economic damages, the base figure adjusters commonly use to value pain and suffering in Step 2.
Step 2: Add in Non-Economic Damages (Pain and Suffering)
Pain and suffering (non-economic damages) has no invoice, so adjusters and attorneys estimate it with two common methods: the multiplier method and the per diem method. Neither is set by law, and insurers aren’t required to use either. Both depend on proof of how the injury changed your days. The two methods compare like this:
| Method | How It Works | Example | Fits Best When |
|---|---|---|---|
| Multiplier Method | Economic damages × a factor commonly between 1.5 and 5 | $10,000 × 3 = $30,000 | Injuries are long-term or permanent |
| Per Diem Method | A daily rate × the days you lived with pain | $150 × 120 days = $18,000 | Recovery has a clear end date |
A common per diem anchor is your daily wage. The multiplier rises with injury severity. These ranges are industry conventions, not legal rules:
| Injury Severity | Commonly Used Multiplier | Examples |
|---|---|---|
| Mild | 1.5 to 2 | Sprains or whiplash resolved with a few weeks of physical therapy |
| Moderate | 2 to 3 | Fractures set without surgery, or a concussion with lingering headaches |
| Severe | 3 to 4 | Herniated discs, surgery, months of treatment |
| Catastrophic | 4 to 5 | Traumatic brain injury, spinal cord injury, amputation, permanent scarring |
The multiplier’s base varies by adjuster. Some multiply medical bills alone, others the full economic total, and that choice can swing the result by thousands of dollars.
Nevada caps pain and suffering only in certain case types, such as medical malpractice. A typical car accident claim has no cap. The exception is a crash caused by a state or local government employee acting on the job, where NRS 41.035 limits total damages to $200,000 per claimant.
Punitive damages sit outside this formula and apply only in limited cases, such as a Las Vegas drunk-driving accident where the driver willfully drank or used drugs.
Your economic and non-economic damages together form the gross claim value. Step 3 reduces it by your share of fault.
Step 3: Reduce the Claim by Your Share of Fault
Your share of fault cuts your claim value by the same percentage. Under NRS 41.141, fault decides two things: how much comes off your award and whether you recover at all. You recover nothing if your fault is greater than the combined fault of the drivers you’re suing. At exactly 50%, you still recover half.
On a $100,000 claim, the fault percentages work out like this:
| Your Share of Fault | What You Recover |
|---|---|
| 0% | $100,000 |
| 20% | $80,000 |
| 50% | $50,000 |
| 51% | $0 |
Every 10% of blame an adjuster shifts onto you erases $10,000 from a $100,000 claim. A sudden lane change, a left turn on a stale yellow, a glance at a phone can each become an argument about percentages.
If you share fault with two or more drivers, each generally pays only its own percentage of your damages. Nevada’s modified comparative negligence standard sets how fault is divided among them. Fault decides what you’re owed. Insurance decides what you can collect.
Step 4: Check Your Claim Against Insurance Policy Limits
Insurance coverage usually sets the real ceiling on what your claim can collect, whatever the claim is worth. Nevada law sets the floor in NRS 485.185, which requires every owner of a Nevada-registered vehicle to carry at least:
- $25,000 for bodily injury or death of one person
- $50,000 for bodily injury or death of 2 or more people in one crash
- $20,000 for damage to other people’s property
A driver with only the minimums leaves just $25,000 of coverage for an injury claim that may be worth far more. Three other sources can fill the gap:
- UIM coverage, if your policy includes it, pays damages above the at-fault driver’s bodily injury limits, up to your own policy limit. Uninsured motorist (UM) coverage pays when the driver had no insurance at all. Our team handles Las Vegas uninsured motorist accident claims under both.
- Medical payments (MedPay) coverage, if you carry it, pays reasonable and necessary medical bills from the crash up to its limit, regardless of who caused it.
- A second liable party or policy adds coverage, such as the employer of a driver who was on the job. If the at-fault driver was providing rideshare transportation services through the app, Nevada requires at least $1 million in coverage.
Once you know the available coverage, fees and liens decide what actually reaches you.
What Is Your Las Vegas Car Accident Case Worth After Fees and Liens?
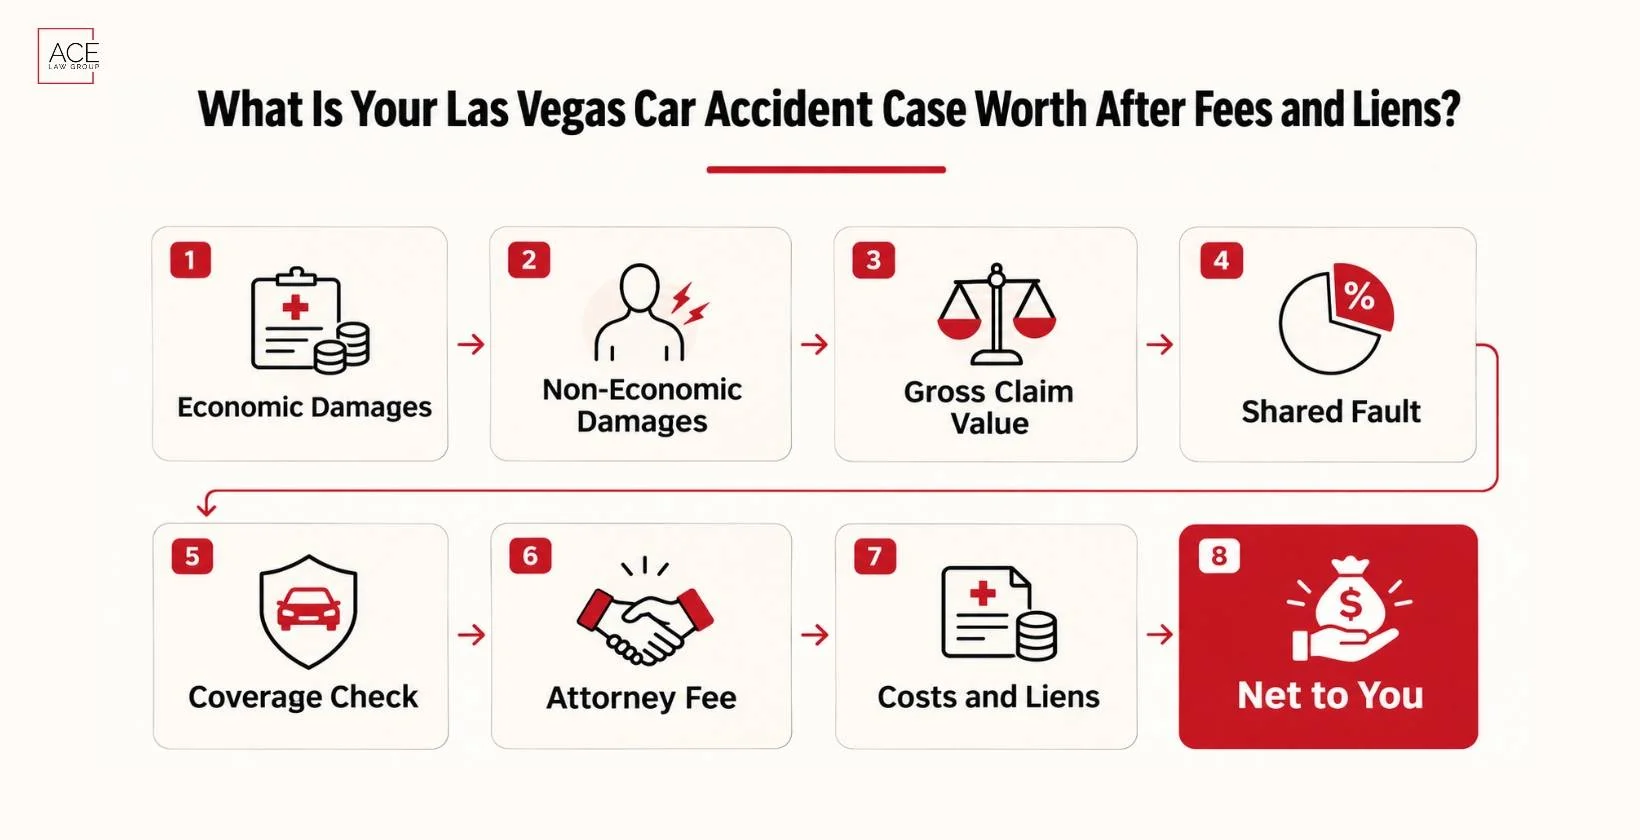
Your net value is what’s left after fault, attorney fees, case costs, and medical liens. That net figure is the amount that reaches your bank account.
Picture a Las Vegas driver rear-ended on I-15 near the Spaghetti Bowl, with a herniated disc treated over 5 months of physical therapy and injections. These figures are illustrative and don’t describe a past case:
- Economic damages: $18,000 in medical bills + $6,000 in lost wages = $24,000
- Non-economic damages: $24,000 × a 2.5 multiplier = $60,000 (the per diem method at $200 × 150 days gives $30,000, a gap worth arguing over)
- Gross claim value: $24,000 + $60,000 = $84,000
- Shared fault: 10% assigned to you, so $84,000 − $8,400 = $75,600
- Coverage check: the at-fault driver’s $25,000 minimum pays first, and your UIM coverage carries the remaining $50,600 if its limit is high enough
- Attorney fee: 33% of $75,600 = $24,948
- Costs and liens: $1,200 in case costs and a $5,000 health plan reimbursement claim
- Net to you: $75,600 − $24,948 − $1,200 − $5,000 = $44,452
Without UIM coverage, the same claim collects $25,000 from the at-fault driver’s policy, and the remaining $50,600 depends on that driver’s personal assets.
This example uses a 33% fee for illustration. Our guide to the fees of car accident lawyers in Las Vegas covers typical ranges. Nevada requires a written contingency fee agreement signed by the client. The agreement states the percentage and whether costs come out before or after the fee.
Liens like the $5,000 health plan claim are often negotiable. Hospital liens and employer health plans follow different rules. Our guide on how to handle medical bills after a car accident explains which kind you’re facing.
That math assumes a fair starting number, and the insurer’s first offer rarely is one.
Is the Insurance Company’s Offer What Your Claim Is Really Worth?
Usually not. The first settlement offer often comes before your treatment ends, and the at-fault driver’s insurer owes its duty to its own policyholder, not to you. Many large insurers run claims through claim-evaluation software such as Colossus. The adjuster enters injury codes and treatment details, and the software returns a value range for pain and suffering. Five file details commonly push that range lower:
- Treatment gaps between appointments
- A late first doctor’s visit
- Prior injuries in your medical records
- Light vehicle damage in photos
- A casual “I’m feeling better” in a recorded statement
The right evidence for a car accident claim keeps those details from lowering your offer.
Timing matters as much as your file. A signed release ends your claim, even if the full cost of your injury isn’t known yet. That cost becomes clear at maximum medical improvement (MMI), when your doctor says your condition has stabilized and future care can be priced. A settlement signed in month 2 can’t account for a surgery recommended in month 6.
Waiting has limits, though. Nevada generally gives you 2 years from the crash to file an injury lawsuit under NRS 11.190, with exceptions covered in our guide to the statute of limitations for car accident claims.
Frequently Asked Questions on Car Accident Claim Value
Is $50,000 a Good Settlement for a Car Accident in Las Vegas?
A good settlement depends on your claim’s gross value, the at-fault driver’s policy limits, and your net. A soft tissue claim with $8,000 in medical bills may be valued at about $20,000 to $24,000, so $50,000 compares well. A fractured hip that needed surgery can be worth far more. After a 33% fee, $50,000 nets $33,500 before costs and liens. Compare any offer with the average car accident settlement in Las Vegas.
Does Health Insurance Paying My Bills Lower My Claim’s Value?
No. Health insurance paying your bills doesn’t lower your claim’s value. Nevada’s collateral source rule bars the defense from using those payments as evidence for any purpose, under Proctor v. Castelletti (1996). Your health plan can still seek repayment through subrogation, and that repayment comes out of your recovery.
Can I Reopen My Claim if My Injuries Get Worse After Settling?
No. In nearly every case, you can’t reopen your claim after signing the release. Courts undo a release only in rare situations, such as fraud. Before you sign, wait until your doctor confirms MMI. Check your UIM policy for a consent-to-settle clause, which can require your carrier’s approval first.
How Long Does a Car Accident Claim Take in Las Vegas?
It depends mostly on your recovery. Valuing future care waits until you reach Maximum Medical Improvement (MMI), then the demand and negotiation follow. Clear fault and low policy limits often speed settlement, while disputed fault or a lawsuit takes longer.
How Is a Claim Valued if a Loved One Died in the Crash?
The claim is valued under NRS 41.085, Nevada’s wrongful death statute, which splits damages between family and estate. Heirs recover for grief, lost support, companionship, and the pain the person suffered. The estate recovers medical bills, funeral costs, and any punitive damages the person would have recovered. Our Las Vegas wrongful death lawyer team documents the family’s share and the estate’s share.
Is My Car Accident Settlement Taxable in Nevada?
No, for most of it. Nevada has no state income tax, and 26 U.S.C. § 104(a)(2) excludes compensation for physical injuries, including lost wages. Punitive damages and interest are taxable. Our answer on whether car accident settlements are taxable in Nevada covers emotional distress awards and earlier medical deductions.
What Does It Cost to Have Ace Law Group Value My Claim?
Nothing upfront. The case review is free, and our fee is a percentage of any settlement or verdict, so you owe no fee unless we recover compensation. We advance case costs, and your signed agreement states whether you repay them without a recovery. If a case is lost, you may be liable for the opposing party’s attorney fees and costs.
Is Your Settlement Offer Fair? Let Us Review It
Bring the offer letter, your medical bills, and the other driver’s insurance information to a free case review. We’ll walk through each step of your claim’s value with you before you decide anything.
Call 702-333-4223 or contact us online. Our office is at 6480 W Spring Mountain Rd, Suite 1, Las Vegas, NV 89146, and our team speaks English, Spanish, Chinese, and Korean. You owe us no fee unless we recover money for you.
We Fight Until the Number Is Right